
Quick summary
Europe’s and Asia’s airlines are letting their fuel hedges run out just as jet fuel sits near double pre-conflict levels. Ryanair chief executive Michael O’Leary says European fares will need to rise 15–20% to absorb the cost. Finnair has only 34% of its 2027 fuel needs covered, while Ryanair is hedged about 80% through March 2027. Major US carriers hold no material hedges at all.
One European budget carrier has already reversed fare increases after passengers refused to pay them. The protection that kept ticket prices from reflecting the full fuel shock expires during 2027.
IATA‘s Jet Fuel Price Monitor put the global average at $196.70 a barrel for the week reported October 27, a 2.2% weekly increase and roughly double the level recorded before the Middle East conflict entered its ninth month.
Aircraft do not fly on goodwill. Jet fuel accounts for 30–40% of an airline’s operating costs, and the financial instruments that smoothed that line item — fuel hedging — are being wound down across Europe and Asia at precisely the wrong moment.
For travellers, the translation is direct: trips booked into 2027 should be planned around higher fares, thinner schedules and fewer fare sales, not around the discounting that defined the past two years. Exposure runs along the Europe–Asia-Pacific long-haul corridor first, because European and Asian carriers have historically hedged more than their US rivals and therefore have more cover to lose. It reaches US domestic and transatlantic bookings too, since American, United, Delta, JetBlue and Allegiant carry no material fuel hedges whatsoever.
Norwegian Air Shuttle has already shown where the ceiling sits: it raised fares after the conflict escalated, then reversed some of those increases when passengers refused to pay them.
Why the fuel cover disappears during 2027
The mechanism is simple enough. A hedge fixes the price of fuel an airline expects to burn months in advance, converting an unpredictable cost into a known one. It cannot make that fuel cheap — locking in today’s price means accepting today’s price. That is the trap carriers are now describing, and it explains why the response has moved from buying protection to cutting flying.
Ryanair stopped adding new hedges in September and covers roughly 80% of its needs only through March 2027. O’Leary’s read is that no European carrier, his own included, is well hedged beyond that point. Finnair‘s January–September 2026 interim report put its average hedging ratio at 34% for 2027, leaving about two-thirds of next year’s fuel bill exposed to the spot market, and the airline has stopped adding new positions.
Capacity is doing part of the work instead. Ryanair held its winter schedule broadly flat year over year and cut its annual traffic target from 216 million to 214 million passengers, a reduction management expects to save €70 million to €100 million in winter losses. That arithmetic translates into fewer seats on some winter markets — fare pressure that arrives before any surcharge does. Lufthansa has trimmed capacity on selected routes for the same reason, and in Malaysia AirAsia is budgeting for twelve months of high oil prices while refusing to model a scenario in which they fall.
Finnair‘s outlook and guidance frames the risk as more than money: a prolonged conflict could affect fuel availability as well as price, with knock-on effects for capacity and schedules.
Fare inflation is already underway. Official indices put EU air fares 5.8% higher year on year in September, with US fares up more than 20% over the same period — and both figures predate the expiry of most existing hedge cover.
| Carrier | 2027 hedge cover | Stated response | What it means for bookings |
|---|---|---|---|
| Ryanair | ~80% through March 2027 | Winter capacity flat; traffic target cut to 214m | Fewer seats on some winter markets |
| Finnair | 34% average for 2027 | No new hedges; flags fuel availability risk | Possible schedule and fare changes |
| AirAsia | Winding down | Budgeting 12 months of high oil; no fall scenario | Fares or cost cuts, not cover |
| Lufthansa | Not disclosed | Capacity cut on selected routes | Route-level seat reductions |
| American, United, Delta, JetBlue, Allegiant | None material | Fully exposed to spot prices | Fares follow fuel directly |
| Southwest | Programme ended | No active position | Full exposure into 2027 |
For the corridor at the centre of this story, flights from Europe to Asia-Pacific destinations remain widely bookable. The open question is what they cost when they are rebooked next year.
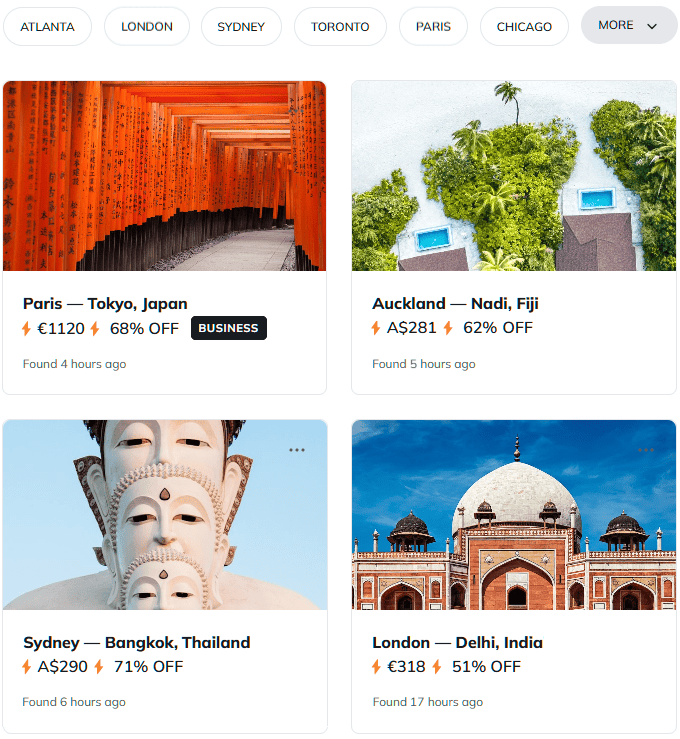
Superdeals cover departures from North America, Europe and Australia.
Flight deals most people never see
Air Traveler Club monitors thousands of routes for pricing anomalies that traditional search engines miss. With ATC Superdeals members save up to 80% on each flight vs. regular fares.
Too good to be true? Check it out yourself. It's free.
Delivered weekly. Unsubscribe anytime.
Hedging was never insurance — and the bill lands later
Hedging is usually described as insurance. It is closer to a position — a wager that fuel will cost more later than it does today — and it only looks clever in hindsight. What it reliably delivers is a known number on a spreadsheet, which is why European and Asian carriers kept buying it long after their US counterparts walked away following costly earlier bets. Those US carriers now absorb every price move in full, which is the part of this story most travellers have backwards.
Treasury teams rarely stop hedging because prices are high. They stop because the forward curve no longer offers anything worth buying. That is the signal buried in Ryanair’s September decision, and it is why the conversation inside these airlines has shifted from procurement to schedule planning.
The second question is whether the flagged 15–20% increase sticks. Norwegian’s reversal suggests a ceiling: passengers will absorb some increase, not any increase. When fares meet resistance, carriers reach for the other lever — fewer seats — which lifts prices without a fare-change announcement. Air Traveler Club’s deal tracking still surfaces short-lived price drops on Asia-Pacific routes, usually lasting three to seven days; useful for a trip you can take soon, but not a guide to what 2027 will cost.
Booking Europe–Asia travel before the cover runs out
Hedge cover thins progressively through 2027, so the decisions that matter now are about flexibility rather than price.
- Pay for changeability where the premium is small. A modest flexibility fee costs less than rebooking a non-refundable ticket after a schedule change.
- Check the schedule, not just the fare, on winter 2026–27 routes. Ryanair’s flat winter capacity means fewer recovery options if a flight moves.
- Watch Finnair’s updates if you connect through Helsinki. Fuel availability risk is capacity risk, and capacity changes surface on schedules before they surface on fares.
- Do not read a sale as a forecast. Promotional pricing reflects today’s inventory, not next year’s fuel bill.
Watch: Ryanair’s summer 2027 schedule release and its next quarterly filing — that is where a flagged 15–20% increase either becomes a published fare or quietly becomes a capacity cut instead.
Reporting by
Questions? Answers.
Will European fares really rise 15–20% in 2027?
That figure is Ryanair chief executive Michael O’Leary’s estimate, and it functions as a signal rather than a commitment. Norwegian Air Shuttle’s reversal of post-conflict fare increases shows there is a limit to what passengers will pay, so part of the adjustment is likely to arrive as fewer seats rather than higher published fares.
Do US carriers hold fuel hedges?
Almost none. American, United, Delta, JetBlue and Allegiant hold no material hedges, Frontier has no active position, Southwest ended its programme, and Alaska and Hawaiian have closed out remaining positions. Their fares track fuel costs more directly than European carriers’ have in recent years.
What is fuel hedging, in plain terms?
A contract that fixes the price of jet fuel an airline expects to buy in future months. It buys cost certainty but locks in today’s price, so it protects against increases and works against the airline when prices fall.
How long does this affect my trip?
Through 2027 at least. Hedges placed before the conflict roll off during the year, and Ryanair’s cover runs only to March 2027. Travel dates in the second half of 2027 carry the most exposure.


