Quick summary
Ryanair has cut its fiscal-year 2027 passenger target from 216 million to 214 million, trimming its winter schedule to reduce exposure to unhedged jet fuel costs currently running near $140 per barrel. The airline warned on 2 September 2026 that if oil prices remain elevated through to summer 2027, short-haul fares across Europe will rise materially — with weaker, less-hedged competitors potentially failing before the season even begins.
Ryanair has locked in 80% of its fuel needs at $67 per barrel, giving it a structural cost advantage over rivals. The winter capacity reduction is expected to cut seasonal losses by €70–100 million.
Europe’s short-haul fare floor is cracking. Ryanair confirmed on 2 September 2026 that it is pulling back its winter flying program and lowering its full-year traffic goal to 214 million passengers — down from 216 million — as unhedged jet fuel costs bite into the seasonally weak off-season. The move is deliberate and the message is blunt: if oil stays where it is, fares go up next summer, and some carriers may not be around to compete.
Brent crude touched $97.04 a barrel on Wednesday before easing to just below $95 — its highest point since late July — supported by OPEC+ supply restraint and ongoing disruptions around the Strait of Hormuz and Red Sea shipping lanes. Jet fuel is tracking close behind, with the global average near the mid-$150 per barrel range according to IATA’s fuel monitor.
For travelers planning intra-European trips in winter 2026–27 or summer 2027, this is not background noise. It is a direct signal that the era of reliably cheap short-haul seats — built on thin margins and aggressive capacity growth — is under pressure from a cost structure that the weakest players cannot absorb.
What Ryanair’s numbers actually say about next summer
The Reuters report confirming the revised traffic target also noted that Ryanair expects passenger numbers between November and March to remain broadly flat versus last winter — the reduction is about shifting aircraft toward markets with lower taxes and better incentives, not grounding planes. The €70–100 million improvement in winter losses comes from flying smarter, not less.
Summer is a different picture. Ryanair’s April-to-October passenger count is on track to reach 145 million, up from 138 million — growth of more than 5%. August and September fares are drifting modestly lower compared with last year, consistent with earlier guidance, but the airline’s warning is forward-looking: summer 2027 fares, not 2026, are where the repricing risk sits.
The mechanism is hedging. Ryanair has covered 80% of its jet fuel needs through March 2027 at approximately $67 per barrel — well below current spot prices — and has already begun locking in around 15% of the following year’s fuel at about $85 per barrel. That buffer keeps the airline profitable for the year, though below last year’s record after-tax profit. Rivals without comparable coverage face the full weight of today’s spot market on their unhedged volumes.
| Carrier | Hedge coverage (FY27) | Locked-in price | Winter capacity stance |
|---|---|---|---|
| Ryanair | ~80% | ~$67/barrel | Cutting — shifting to lower-tax markets |
| Wizz Air | ~76% | ~$819–826/metric ton (zero-cost collars) | Growing — mid-teens capacity increase planned |
| easyJet | ~72% (H2 2026) | ~$726/metric ton | Cautious — warns on unhedged spot exposure |
The Guardian’s coverage of the same announcement highlighted Ryanair’s explicit warning that less well-hedged competitors will struggle to maintain capacity or may fail this coming winter — language that is unusually direct for a scheduled trading update.
Meanwhile, Wizz Air reported passenger growth of 25.9% in August year on year, reaching approximately 8.7 million passengers for the month. Its Q1 FY27 results filing confirms it is pushing into markets where competitors are pulling back — a calculated bet that demand holds and spot fuel does not spike further.
For travelers booking short-haul flights within Europe, the divergence between these three carriers matters more than any single fare announcement.
Flight deals
most people never see
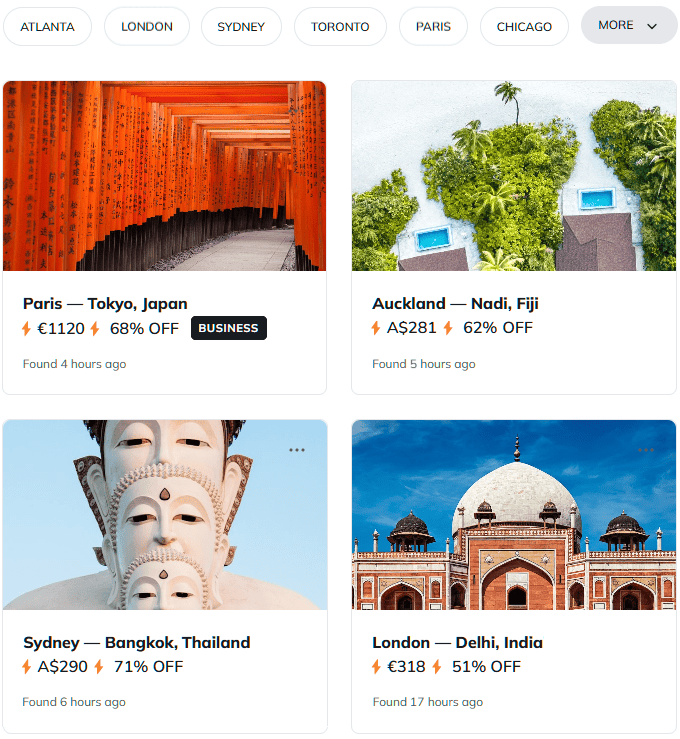
Our AI monitors 150+ airlines for pricing anomalies that traditional search engines miss. Air Traveler Club members save $650 per trip per person on average: see how it works.
Each deal saves 40–80% vs. regular fares:
Why the hedging gap is the real story for 2027 fares
Fuel typically accounts for 25–35% of a low-cost carrier’s operating costs. When spot prices run $70–80 above a carrier’s locked-in rate — as they do today for airlines without Ryanair’s hedge position — the unhedged portion of every flight becomes a direct margin drain. Carriers with thin cash reserves cannot absorb that indefinitely.
The three major European budget carriers are entering this winter from meaningfully different positions. Ryanair’s $67 per barrel lock-in is the most favorable; easyJet’s coverage at around $726 per metric ton sits in the middle; Wizz Air’s zero-cost collars cap out near $819–826 per metric ton — higher than easyJet’s, though the collar structure limits downside exposure too. None of them are fully exposed to spot prices, but all three carry unhedged volumes that become more expensive with every week crude stays above $90.
The carriers most at risk are not these three. They are the smaller, regional operators — leisure-focused airlines with limited hedging programs and thinner balance sheets — whose routes often undercut the majors on price. If one or two exit specific city pairs this winter, the remaining seats on those routes reprice upward fast. That is the scenario Ryanair is flagging, and it is not hypothetical: European aviation has seen exactly this dynamic before, most recently when Norwegian Air’s short-haul operation collapsed in 2020 and fares on several Scandinavian routes jumped within weeks.
Steps to protect your 2027 European travel budget
Ryanair’s capacity cut is already filed; the fare repricing it warns of is conditional on oil staying elevated — but with Brent above $94 and OPEC+ showing no sign of reversing supply restraint, that condition is closer to baseline than tail risk.
- Book summer 2027 intra-European legs now, not in spring. Ryanair’s summer schedule is open. If you have fixed travel dates, the current fare environment — with August and September 2026 fares drifting modestly lower — is likely the softest pricing window before hedging costs roll through to 2027 tickets.
- Cross-check Wizz Air on Central and Eastern European routes. Wizz is actively growing into markets where Ryanair is pulling back, particularly in Italy, the UK, and Central Europe. On those corridors, competitive pressure may keep fares lower for longer — but Wizz’s higher capped fuel costs mean its buffer is narrower than Ryanair’s.
- Treat flexible fares differently on thin-served routes. On city pairs with only one or two low-cost operators, consider refundable or changeable tickets booked a few months earlier than usual. If a weaker carrier cuts that route mid-winter, remaining seats on Ryanair or easyJet will not be cheap.
- Set fare alerts on routes you’re not ready to book. Tools like Google Flights and Skyscanner will catch any downward movement before the market tightens. The window for acting on those alerts will be shorter than in previous years.
- Watch easyJet’s H1 2027 hedging update. The airline’s next disclosure will show whether it has extended coverage at current prices or left more volume exposed to spot — a meaningful signal for fare direction on its network.
Watch: OPEC+’s next supply decision and any Strait of Hormuz escalation are the two variables that could accelerate or reverse this entire scenario. A crude price drop back toward $80 would relieve pressure on unhedged carriers and likely stabilize fares; a move above $100 would bring Ryanair’s warning much closer to certainty.
Questions? Answers.
Which European routes are most at risk of higher fares in summer 2027?
Routes served primarily by smaller, leisure-focused carriers with limited hedging programs face the sharpest risk — particularly leisure-heavy city pairs in Central and Eastern Europe and regional Western Europe where Ryanair and Wizz Air do not dominate. If a weaker carrier exits one of these routes, remaining seat supply tightens quickly and fares on the surviving carrier reprice upward.
Does Ryanair’s winter capacity cut mean fewer flights on my route?
Not necessarily on the route level. Ryanair has stated that total winter passenger numbers will remain broadly flat versus last year — the reduction is about shifting aircraft toward markets with lower airport taxes and better incentives, not eliminating routes outright. However, specific thin-demand routes may see reduced frequency, so checking your route’s winter schedule directly on Ryanair’s site is worthwhile.
Is Wizz Air a safer bet for cheap fares if Ryanair is cutting capacity?
Wizz Air is growing aggressively and may offer competitive fares on routes where it is expanding — particularly in Central and Eastern Europe, Italy, and the UK. However, its fuel hedge caps out at a higher price than Ryanair’s, meaning its cost buffer is narrower. If spot fuel prices rise further, Wizz faces more pressure on its unhedged volumes than Ryanair does, which could eventually affect its pricing too.
When will it become clear whether summer 2027 fares actually rise materially?
The clearest signal will come from Ryanair’s winter trading update, typically published in late January or February 2027, which will show whether oil has stayed elevated and whether any smaller competitors have reduced capacity or exited routes. easyJet’s next hedging disclosure will also indicate how much of its 2027 fuel exposure remains unprotected. By March 2027, when summer schedules are largely set and seat inventory is live, the fare direction will be visible in booking data.