
Quick summary
From December 8, 2026, Qantas Frequent Flyer members in Australia can earn Status Credits from ten everyday spending categories — including banking and home loans — capped at 140 Status Credits per membership year. The ground-earning layer is permanent, not a limited promotion, and credits post within eight weeks of a member clearing a category threshold.
The cap covers less than half the 300 credits needed for Silver, so flying still decides tier outcomes. A new Atlas home loan, funded by ColCap Financial Group, opens refinance-only at 6.27%.
Qantas has found a new way to sell status, and it runs through your mortgage. From December 8, 2026, members of Qantas Frequent Flyer in Australia will collect Status Credits from ten everyday spending categories — and for the first time, banking and home loans sit among them.
The practical effect is narrow but real. Ground activity can top up a tier, not replace the flying that earns it. Qantas caps the whole scheme at 140 Status Credits per membership year, against the 300 needed for Silver and 700 for Gold.
The change is aimed at Australian members and Australian-linked products, so it does nothing for overseas cardholders. Credits post within eight weeks of a member clearing a category threshold, which gives anyone chasing a tier a defined window to plan around.
The launch arrives with a second piece of news: ColCap Financial Group has joined Bendigo and Adelaide Bank as a funder of Qantas Money Home Loans, bringing a refinance-only Atlas range priced at 6.27% variable.
What the ten categories cover — and what 140 credits actually buys
Ten categories open on December 8, 2026: credit cards; banking and home loans; insurance; car; home utilities; hotels and accommodation; holidays and experiences; everyday shopping; retail and lifestyle; and sustainability. Qantas has published the full list on its Status Credits on the ground page.
Banking and home loans count as one combined category rather than a mortgage-only allowance, and no standalone Status Credit value for a home loan has been announced.
The ceiling across all ten is 140 Status Credits per membership year, with credits landing within eight weeks of a member clearing a category threshold. Against Qantas’s published tier table — 300 credits to reach Silver, 700 for Gold, and 250 and 600 to retain them — the ground layer is a supplement, not a substitute.
That distinction matters more than the headline number. A 140-credit ceiling is enough to rescue a tier for a member who flies a handful of times a year, and nowhere near enough to manufacture one from scratch.
| Factor | Before December 8, 2026 | After |
|---|---|---|
| Status Credit sources | Flights and eligible partner activity | Adds ten ground spending categories |
| Annual ground cap | None | 140 Status Credits per membership year |
| Banking and home loans | Points only | Points plus Status Credits |
| Atlas home loan | Not offered | Refinance only, 6.27% variable, 6.63% comparison rate |
| Credit posting | Not applicable | Within eight weeks of clearing a threshold |
On the lending side, ColCap Financial Group joins Bendigo and Adelaide Bank as a second funder of Qantas Money Home Loans. Its new Atlas range is refinance-only for now, with purchase products planned, and it carries a published variable rate of 6.27% and a comparison rate of 6.63%, lending to a maximum 80% loan-to-value ratio. Qantas Money has settled more than $3 billion since launching in February 2023, with new loans up 30% year on year. Demand has concentrated among borrowers and property investors on Australia’s eastern seaboard moving away from the major banks.
An eligible loan settling earns 100,000 points, plus another 100,000 points each year for the life of the loan. Five years of holding gives 600,000 points — which Qantas describes as enough for two return Business Classic Flight Reward seats between Sydney and Los Angeles.
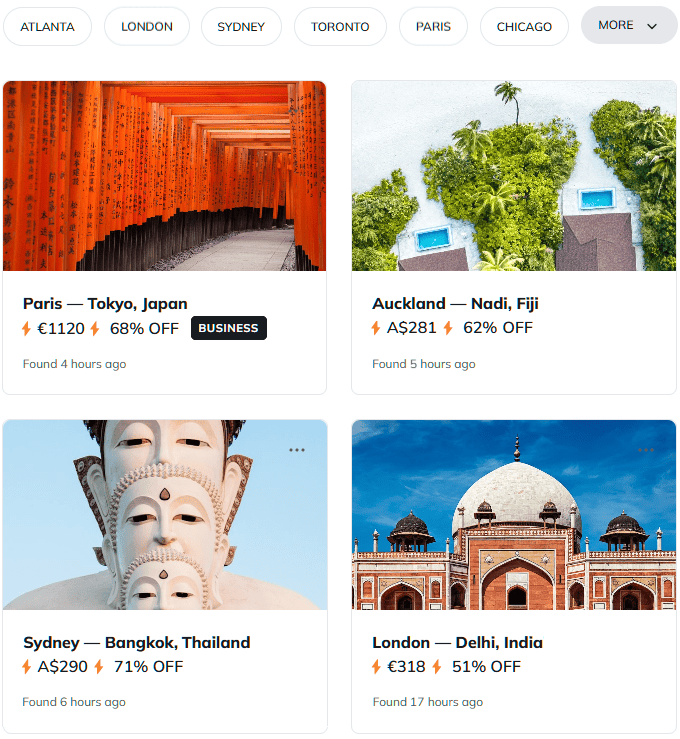
Superdeals cover departures from North America, Europe and Australia.
Flight deals most people never see
Air Traveler Club monitors thousands of routes for pricing anomalies that traditional search engines miss. With ATC Superdeals members save up to 80% on each flight vs. regular fares.
Too good to be true? Check it out yourself. It's free.
Delivered weekly. Unsubscribe anytime.
Why Qantas is pricing status in mortgage payments
Loyalty programs stopped being marketing departments years ago. They are balance-sheet assets, and Qantas is now using one to feed the other. A mortgage book that has settled more than $3 billion since 2023 gets a fresh reason to exist, and the frequent flyer program gets a new category of member behaviour to monetise. ColCap brings a 20-year record and a $25 billion home-loan portfolio to the panel, which suggests the airline wanted lending capacity rather than a marketing partner.
The arithmetic, though, is deliberately modest.
A full 140 ground credits equals 46.7% of the 300 needed for Silver and 20% of the 700 for Gold, before Qantas’s separate flight conditions are applied. Members a few credits short of retaining a tier will find the pathway useful. Members who barely fly will not reach Silver on banking alone.
The existing Qantas Money range stays in place alongside Atlas, so the partnership widens the menu rather than replacing it.
Two decisions, and the order to make them in
Two decisions sit inside this announcement, and they should be made in order — the mortgage first, the status planning second. Atlas is refinance-only, capped at 80% loan-to-value, and priced at 6.27% variable with a 6.63% comparison rate. Those are published figures rather than a personal quote, and they move. Run them against refinance offers from the major Australian banks before deciding whether the points and future ground Status Credits justify any gap.
On the status side, Qantas has confirmed that ground credits will not be awarded for activity completed before December 8, 2026, so nothing done this year counts toward the 140. Once the scheme is live, track category progress in your account. The eight-week posting window matters when you are timing a retention.
The points math runs on the full term, not the first year. A settling loan earns 100,000 points, then 100,000 a year for as long as you hold it — five years is 600,000 points, which Qantas describes as two return Business Classic Flight Reward seats between Sydney and Los Angeles. Air Traveler Club’s tracking of temporary fare drops out of Australasia is the other half of that comparison, because points only have a value against the cash fare you would otherwise pay.
Watch: Qantas has not published how the 140 credits split across the ten categories; the per-category allocations will decide whether banking is worth chasing at all.
Reporting by
Questions? Answers.
Can I earn Status Credits from my Qantas home loan before December 8, 2026?
No. Qantas states that Status Credits from ground activity will not be awarded for activity completed before the launch date. Anything you do this year counts toward points only, not toward the 140-credit annual cap.
Will 140 ground Status Credits get me Silver?
No. Silver requires 300 Status Credits to earn and 250 to retain, and Gold requires 700 to earn and 600 to retain. The ground maximum covers less than half of Silver and cannot satisfy Qantas’s separate flight-related conditions on its own.
What rate does the Atlas home loan charge?
Qantas Money’s published listing shows a 6.27% variable rate and a 6.63% comparison rate, refinance loans only, with lending up to 80% loan-to-value. Rates and eligibility can change, so confirm the live offer before applying.
Do I need to be a Qantas Frequent Flyer member to get Atlas?
Yes. ColCap describes Atlas as available exclusively to Qantas Frequent Flyer members, while the existing Qantas Money home-loan products remain separate options funded through Bendigo and Adelaide Bank.


