
Quick summary
American Airlines and Citi are raising the annual fee on the Citi / AAdvantage Platinum Select World Elite Mastercard to $150 from $99, and the Citi / AAdvantage Business Mastercard moves to the same figure. Both changes take effect January 24, 2027, adding $51 a year at the relevant renewal — the first increase for these products since 2018.
New credits soften the blow, but only partly. The $100 inflight credit repeats annually; the $120 trusted-traveler credit arrives once every four years.
American raises AAdvantage card fees for the first time since 2018
American Airlines and Citi confirmed on October 27 that the Citi / AAdvantage Platinum Select World Elite Mastercard will carry a $150 annual fee from January 24, 2027, up from $99. The Citi / AAdvantage Business Mastercard moves to the same number.
Eight years without a change, and the increase lands in a single line: $51 more, every year, for as long as the account stays open.
Nothing happens at midnight tonight. The new pricing applies at each cardholder’s first renewal on or after that January date, which gives existing holders a full billing cycle — sometimes more — to decide whether the card still earns its keep.
The affected group is narrow but well-defined: U.S. holders of the two Citi-issued AAdvantage products. Because those miles feed American‘s international network, including trans-Pacific services and partner-operated flights, the decision reaches well beyond domestic travel. For anyone weighing a long-haul award ticket to Asia, the annual fee is now part of the trip math.
What the new $150 fee actually buys
American and Citi’s official announcement pairs the higher charge with three additions to the consumer card. There is up to $100 a year in statement credits on eligible inflight purchases, up to $120 toward a Global Entry or TSA PreCheck application once every four years, and triple AAdvantage miles on hotel stays booked through American’s own portal. A fourth item — a $150 flight discount — only unlocks after $20,000 in card-year spending and a renewal.
Read the credits closely and a pattern appears. Each one is spent inside American’s own ecosystem: food bought on its aircraft, a hotel booked through its portal, a trusted-traveler application processed by a U.S. government agency the airline already partners with. The card is being repriced as a tool for people who fly American often, not as a general-purpose wallet.
The arithmetic matters more than the headline. A cardholder who uses the full $100 inflight credit faces a net $49 increase before valuing a single mile — a far smaller hit than the $51 figure suggests. Someone who rarely buys onboard, or who books hotels elsewhere, absorbs the whole thing.
| Feature | Before | After | What it means |
|---|---|---|---|
| Annual fee | $99 | $150 | $51 more at the first renewal on or after Jan. 24, 2027 |
| Inflight statement credit | — | Up to $100 a year | Fully used, the net fee falls to roughly $49 |
| Trusted-traveler credit | — | Up to $120 every four years | A one-time offset, not an annual one |
| Hotel earning via American’s portal | — | 3 AAdvantage miles per dollar | Rewards booking through American rather than elsewhere |
| Flight discount | — | $150 after $20,000 card-year spend | Clears only for heavy spenders |
The trusted-traveler credit deserves a second look, because it is the benefit most likely to be misread. Global Entry‘s standard application fee is $120, which is exactly what the credit covers — but it recurs once every four years, so it cannot be counted against an annual fee. Treat it as a one-off rebate, not a subscription perk.
For travelers building award itineraries, the earning side still runs through flights from North America to Asia-Pacific destinations, where AAdvantage miles and partner redemptions remain the practical currency.
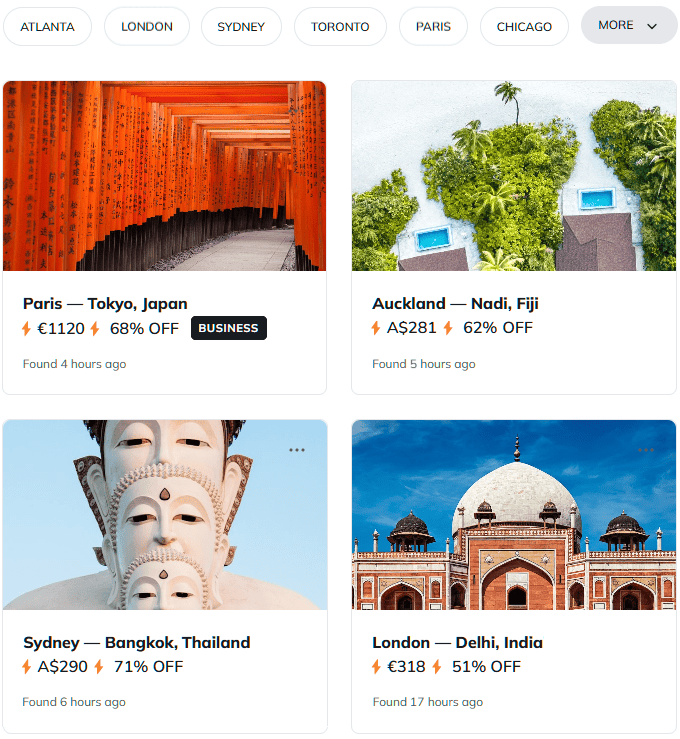
Superdeals cover departures from North America, Europe and Australia.
Flight deals most people never see
Air Traveler Club monitors thousands of routes for pricing anomalies that traditional search engines miss. With ATC Superdeals members save up to 80% on each flight vs. regular fares.
Too good to be true? Check it out yourself. It's free.
Delivered weekly. Unsubscribe anytime.
Why every premium travel card is getting more expensive
American’s move is not an outlier — it is a confirmation. American Express lifted its Platinum card to $895 from $695, and Chase‘s Sapphire Reserve now sits at $795, up from $550. United Airlines has pushed fees higher on its own co-branded products. The direction of travel across the U.S. premium-card market has been one-way for several years.
Here is the part the marketing copy skips: airlines almost never lower a fee. They add a credit, tie it to their own booking channel, and let the headline number climb. Co-branded cards are a multi-billion-dollar revenue line for U.S. carriers precisely because banks buy miles in bulk and hand them out as rewards — the airline books the revenue whether or not the cardholder ever flies.
Expect the standard sequence from here. Competitors typically respond within a renewal cycle, either by matching the fee or by adding a comparable credit. Retention offers tend to surface closer to the effective date, when cardholders actually call to cancel.
For travelers who would rather pay cash than burn miles on a trans-Pacific award, Air Traveler Club’s tracking of temporary fare drops from North America occasionally flags prices well below the mileage equivalent.
How to decide before your next renewal
The deadline is not January 24 itself — it is your own renewal date, which may fall months later. Find it first, then run the numbers against your actual spending rather than the advertised benefit list.
Start with the inflight credit. If you reliably buy food or drinks on American flights, the $100 is close to cash and the real increase is about $49. If you bring your own snacks, it is worth nothing, and the full $51 stands. Then check whether you book hotels through American’s portal at all — triple miles on stays you were going to book elsewhere is free value; triple miles on stays you would never route through the airline is not.
The $20,000 spending threshold for the flight discount is the clearest dividing line. That is roughly $1,667 a month on one card, and the reward is a $150 discount — under 1% back on the qualifying spend. Frequent flyers who already concentrate spending there will clear it without trying. Everyone else should ignore it entirely when comparing cards.
Bottom line: if you use the inflight credit and fly American regularly, the card survives the increase; if you hold it mainly for the sign-up bonus, the math no longer works.
Reporting by
Questions? Answers.
When exactly does the higher annual fee apply?
The $150 fee takes effect January 24, 2027, and applies at each cardholder’s first renewal on or after that date. If your renewal falls in March 2027, that is when you pay the new amount — not in January.
Does the $120 Global Entry credit cover the fee increase?
No. The credit is available once every four years and matches Global Entry‘s $120 application fee. Spread across four years, it offsets about $30 annually — useful, but not a yearly rebate.
Do both the consumer and business cards get the same new benefits?
American and Citi announced the $150 fee for both products. The detailed credit package described in the announcement applies to the consumer card, so business-card holders should confirm their specific terms with Citi before renewing.
Is it worth cancelling over $51?
Only if you were not using the card’s American-specific benefits. Cancelling also removes the account’s age from your credit history and forfeits any accumulated AAdvantage miles tied to the card relationship, so the decision is rarely about the fee alone.


